 News Desk
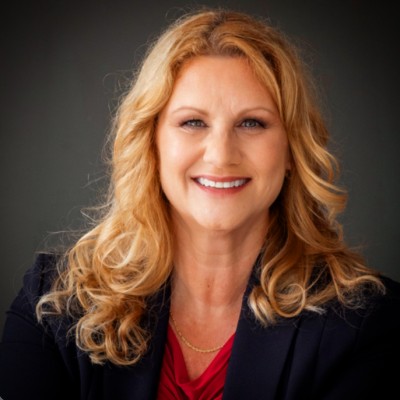
Indrajit Agarwal, Senior Research Analyst at CLSA, expects cement prices to improve after the monsoon, supporting a recovery in profitability as costs stabilise. He prefers large-cap cement companies, citing better visibility on volume growth and cost savings, with Ultratech Cement as his top pick. He also expects industry consolidation to continue, mainly through organic capacity additions.
Cement demand in India is turning out to be stronger than expected, despite pressure on profitability from higher fuel costs and the seasonally weaker second quarter, July to September. Indrajit Agarwal, Senior Research Analyst at CLSA, expects pan-India cement volumes to grow in the mid- to high-single digits in the July-September quarter of 2026 (Q2FY27), with northern and western India seeing particularly strong demand. “Both in the months of July and August, demand has panned out much better than what we had initially expected,” Agarwal said.
However, stronger volumes are unlikely to prevent a near-term hit to margins. Q2 is typically a weaker quarter for cement volumes, which means lower fixed-cost absorption. At the same time, the increase in petcoke prices seen in March, April and May will have its full impact during the quarter.
Agarwal expects the industry to see earnings before interest, taxes, depreciation and amortisation (EBITDA) correction of around ₹200-250 per tonne in Q2, although the impact will vary across companies depending on their region and maintenance costs. Cement prices have remained broadly stable or seen a slight sequential decline in Q2, but Agarwal expects pricing to improve after the monsoon and festive season. Based on channel checks, he expects a 1-1.5% price increase in the second half of the year from September-end levels.
A stronger increase of around 2-3% could come around March-April. If petcoke and coal prices do not rise further, Agarwal expects industry profitability by the end of the financial year to be ₹250-300 per tonne higher than the Q2 level. When it comes to cement stocks, Agarwal prefers large caps because of their better visibility on volume growth and cost-saving initiatives.
He noted that large cement companies are already trading at a discount to their historical valuations, while their more granular cost-saving targets provide greater visibility even if competition remains high and pricing remains difficult. Regional players, meanwhile, can face greater volatility depending on local demand and weather conditions. The east and northeast, for instance, have performed weaker this quarter due to heavier and longer monsoon conditions.
Within the large-cap space, Agarwal has Ultratech Cement as his high-conviction pick, citing its achievable cost-saving guidance and clearly laid-out capacity additions. “Ultratech is on high conviction outperforms for us, followed by the other large cap names,” he said. He also sees value in Shree Cement and Ambuja Cements , noting that both are focusing more on profitability than simply chasing volumes.
Their underutilised capacity could allow them to grow broadly in line with the industry over the next few years. Beyond demand and pricing, Agarwal sees cost reduction as an important structural lever for cement companies. Indian cement makers benefit from the availability of additives such as slag from the steel industry and fly ash from power plants, which reduces clinker usage and helps lower the industry's carbon footprint.
Watch the full conversation here Renewable power and waste heat recovery are also helping companies reduce energy costs while improving their ESG performance. Agarwal believes these initiatives could become increasingly important as intense competition makes it harder for companies to rely on price increases to protect profitability. He also expects consolidation in the cement industry to continue, although increasingly through organic capacity additions rather than acquisitions.
Over the next three to four years, he estimates that around half of the industry's new capacity could be added by companies such as Ultratech. Catch all the latest updates from the stock market here Note To Readers The views and tips expressed by investment experts on CNBCTV18.com are their own, not of the website or its management. CNBCTV18.com advises users to check with certified experts before taking any investment decisions.
Home Market News Cement demand stronger than expected says CLSA’s Indrajit Agarwal, favours Ultratech
Source: cnbctv18.com